

Plynk: Grow as an Investor
4.1

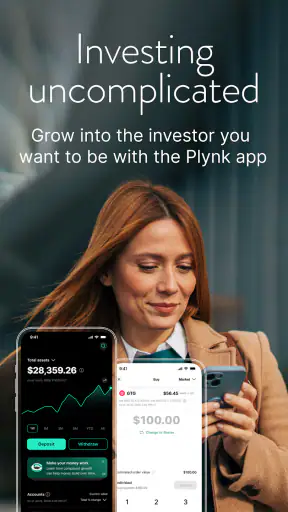
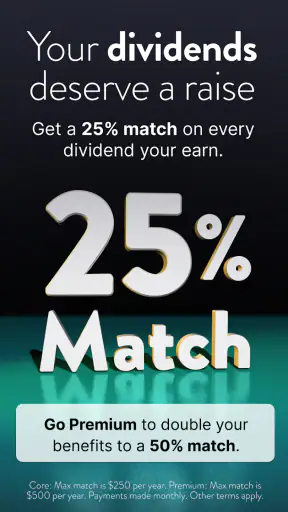
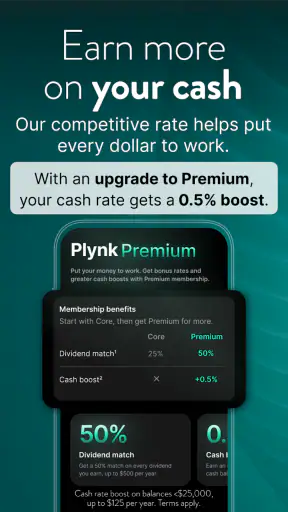
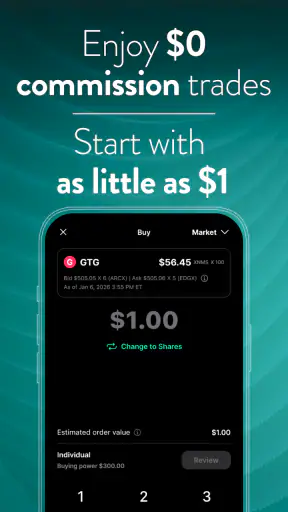
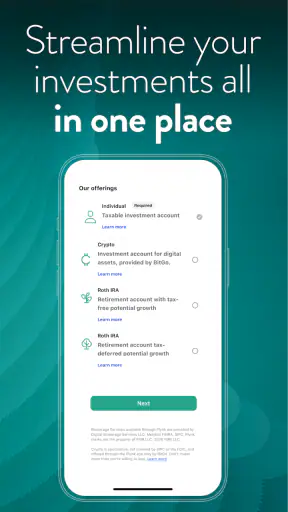
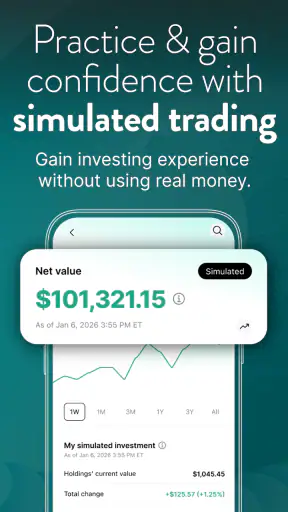
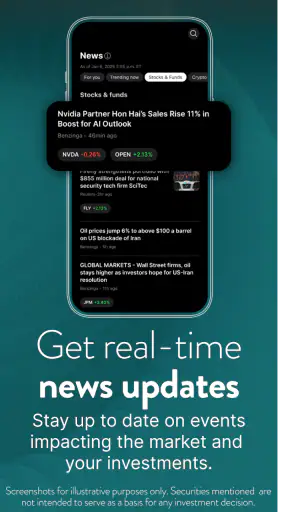
I found Plynk: Grow as an Investor most useful as a friendly starting point for people who want to understand investing before making it part of their routine. It is a free finance app from Digital Brokerage Services LLC, built around clearer explanations and approachable investing tools rather than the intimidating feel that often surrounds brokerage platforms. After spending time with it, my impression is that it works best as a learning companion and a simple way to stay engaged with investing, not as a complete replacement for every tool an experienced investor may already use.
The app is available for Everyone and requires Android or iOS version 12 or later. It has reached over 500 thousand installs and holds a 4.1 average from roughly 4.1 thousand ratings, which suggests that its straightforward approach has found a real audience. I would still treat those numbers as a starting signal rather than proof that it will suit every investor. The important question is whether you want a less intimidating path into investing, or whether you already need advanced research, detailed portfolio controls, and highly specialized trading features.
How Plynk feels in everyday use
The first thing I noticed is the app’s attempt to make investing feel understandable rather than exclusive. Its design direction is centered on intuitive tools and education, and that combination matters. A new investor often does not need more buttons; they need enough context to understand what a choice means before tapping it. Plynk’s appeal comes from putting that learning mindset close to the investing experience instead of treating education as something separate.
That makes it a natural fit for someone who has been curious about investing but keeps postponing the first step. You might be saving regularly, hearing friends discuss markets, or simply wanting to understand how investments differ from cash savings. In those situations, an app that encourages questions and explains concepts in plain language can be more useful than a feature-heavy platform that assumes you already know the vocabulary.
I would not describe it as a toy, but I also would not approach it as a professional workstation. The balance is deliberately tilted toward accessibility. That is a strength when you are building confidence, yet it can become a limitation once your needs become more technical. Investors who want dense charting, complex order controls, detailed tax planning, or a broad research workflow may eventually prefer a traditional brokerage platform alongside, or instead of, Plynk.
A realistic first-week scenario
Imagine a new investor who has set aside a modest amount after paying monthly bills. Instead of immediately searching for the most popular investment, I would use Plynk to slow the process down. I would open the educational material first, note unfamiliar terms, and only then explore the available tools. The practical benefit is not that the app removes risk; no app can do that. The benefit is that it gives the user a better chance of recognizing the difference between learning about an investment and feeling pressured to act.
That workflow is one of the more valuable ways to use it. Treat the app as a place to form a repeatable habit: learn one concept, review what you already understand, and make decisions only when you can explain them to yourself. This is especially helpful for people who tend to make financial choices based on headlines or social media excitement. Plynk’s educational emphasis can provide a pause between seeing an idea and acting on it.
What the current version tells me
The current release is version 4.4.2, and that matters mainly because it shows the product is not frozen at its original launch. Plynk first appeared on April 14, 2021, so the app has had time to develop beyond its earliest form. I would read that evolution as a positive sign for users who want a maintained product, while keeping expectations realistic: a newer version number does not automatically mean that every advanced feature found in larger investment services is present.
For someone already using the app, an updated release can make the experience feel more settled and dependable than an early version. It also means that screenshots or impressions from the launch period may not represent the experience today. When reviewing any financial app, I prefer to judge the current workflow rather than assume that an old complaint or old compliment still applies.
At the same time, version information should not be confused with a promise about future development. I would not install it expecting a particular upcoming tool simply because the product has received updates. The sensible approach is to use what is available now and treat future changes as a bonus. That distinction is important in finance, where your plans should not depend on an unannounced feature.
Who benefits most from the educational approach
Plynk is particularly well suited to three kinds of users. The first is the complete beginner who wants explanations before making decisions. The second is the casual investor who wants investing to feel less disconnected from everyday money management. The third is someone who has tried a conventional brokerage app and found the interface too dense or the terminology too abrupt.
For these users, the app’s strongest quality is the way learning and action sit close together. You can approach a subject, consider what it means, and then decide whether the related tool is relevant to you. That sequence is more responsible than choosing an investment first and researching it only afterward.
I also think it may suit a person who prefers a guided experience over building a portfolio from a blank screen. A blank screen can look flexible, but it can also create unnecessary anxiety. Plynk’s clearer presentation may help users who need structure at the beginning. The trade-off is that people who want to customize every part of their process may find that same structure restrictive.
Where it differs from ordinary brokerage alternatives
Compared with a conventional brokerage app, Plynk places more visible emphasis on helping the user understand investing. Many established platforms are excellent once you know what you want to research or buy, but their interfaces can make beginners feel that they are expected to arrive with a working knowledge of markets. Plynk takes the opposite starting point: it tries to make the learning curve less abrupt.
Compared with a savings app, however, it serves a different purpose. Saving is generally about setting money aside with fewer decisions, while investing involves uncertainty and a need to understand what you are doing. Plynk may help bridge the gap for someone moving from saving toward investing, but it should not be treated as though investment outcomes are as predictable as a savings balance.
Compared with a dedicated education resource, the advantage is convenience. You are learning in the same general environment where investing decisions take place. The disadvantage is that a specialized course, book, or independent research source may offer greater depth and more room for competing viewpoints. I would use Plynk as one part of a learning process, not as my only source of financial knowledge.
Small habits that make the app more useful
My first practical tip is to use the educational material before you need it. Waiting until you are about to make a decision creates pressure, and pressure encourages shortcuts. Browsing with no immediate intention to invest lets you identify concepts that still feel unclear. Later, when a decision matters, you are less likely to confuse a familiar word with genuine understanding.
My second tip is to keep a short personal explanation for every investment idea you consider. Write down what you think it does, why it might belong in your plan, and what could make it unsuitable. This is not a feature claim about Plynk; it is a workflow that makes its educational focus more effective. The app can present information, but the discipline of turning that information into your own reasoning is what protects you from impulsive choices.
A third useful habit is to separate app convenience from financial suitability. An intuitive screen can make a decision feel comfortable, but comfort is not the same as low risk. I would review my time horizon, emergency savings, and ability to tolerate losses outside the app before committing money. Plynk can support the learning process, but it cannot decide whether investing is appropriate for your personal situation.
Finally, I would revisit the app after a quiet period rather than checking constantly. Beginners can easily turn an educational tool into a source of daily anxiety by watching every movement. If your goal is long-term learning, frequent checking may add emotion without adding insight. The most productive use is often a calm review followed by time away from the screen.
What existing users may notice over time
For current users, the product’s evolution from its initial release to version 4.4.2 should make the app feel like an ongoing service rather than a one-off experiment. That is reassuring when you are building a financial habit because consistency matters. A familiar interface and a maintained app reduce the friction of returning to review what you have learned.
Still, existing users should judge each update by its effect on their own routine. A change can improve clarity for a beginner while feeling slower to someone who already knows the basics. It can also shift attention toward education in a way that benefits cautious users but frustrates people who want to move quickly. My advice is to recheck your regular workflow after an update: can you still find the information you need, understand the decision in front of you, and review your activity without unnecessary effort?
The app’s rating of 4.1 from about 590 written reviews reflects a generally favorable reception, but it also leaves room for mixed experiences. I would interpret that as a reminder to test the app against your own expectations. A person looking for approachable guidance may be delighted, while an advanced investor may consider the same simplicity insufficient.
Where the experience still falls short
The biggest limitation is the natural boundary between simplicity and depth. Making investing easier to approach usually means reducing clutter, but experienced users often rely on detail. If your decisions depend on extensive comparisons, specialized analysis, or a highly customized process, you may find yourself reaching for other resources. That does not make Plynk weak; it means its priorities are different.
I also would not choose it as my sole financial reference. Education inside an investing app is useful, but responsible decisions benefit from independent reading and a clear personal plan. The app can help explain concepts and organize an approachable starting point, yet it cannot replace careful consideration of risk, goals, taxes, and changing circumstances.
Another potential source of friction is the expectation that an intuitive interface will make investing effortless. It can make navigation easier, but the underlying decisions remain important. If you want a completely passive experience with minimal involvement, a different type of financial product may suit you better. If you want full control over every technical detail, a more advanced brokerage may be the better choice.
I would also skip Plynk if you are searching for a platform primarily for professional-level analysis or complex trading workflows. Its identity is clearer when viewed as an approachable finance app for learning and participating, not as a replacement for every specialist tool. Choosing it for the wrong reason could leave you disappointed even if the app is well designed for its intended audience.
Questions I would consider before installing
If you are wondering whether it costs anything to try, Plynk is free. That removes one common barrier for a curious beginner, although free access should not be confused with risk-free investing. Your attention, decisions, and invested money still deserve the same care you would give them on any other platform.
If you are asking whether it is suitable for a child, the Everyone content rating describes the app’s general content classification, not personal financial readiness. I would focus less on the label and more on whether the user understands investing risk, can make responsible decisions, and has appropriate guidance. An age category does not turn a financial decision into a simple one.
If you are unsure whether your phone can run it, the minimum operating-system requirement is version 12. That is worth checking before planning your workflow, especially if you use an older device. A smooth financial routine depends partly on reliable access, so compatibility is a practical detail rather than an afterthought.
If you are comparing it with a familiar brokerage, ask yourself what you are missing today. If the answer is confidence, explanations, and a calmer introduction, Plynk is worth considering. If the answer is complex analysis, specialized controls, or a professional research environment, another platform may be more appropriate. The best choice depends on the problem you are actually trying to solve.
What I would watch next
I would watch how the app continues balancing education with efficiency. New users need context, but returning users need a quick way to review their plans and act without unnecessary repetition. The strongest future direction would preserve the welcoming tone while giving experienced users more control over how much guidance they see.
I would also pay attention to whether future releases make the learning process more practical. Explanations are valuable, but the real test is whether users can apply them when comparing choices, reviewing progress, or reconsidering a decision. Improvements that connect knowledge with thoughtful action would matter more to me than cosmetic changes.
My overall view is positive but specific: Plynk is a strong entry point for learning-oriented investors who want investing explained in a less intimidating way. I like its focus, its free access, and the fact that it has continued developing since launch. I would recommend it to a friend who wants to begin carefully, especially if conventional brokerage apps feel overwhelming.
I would not recommend it blindly to an advanced investor or to anyone expecting the app to make financial decisions effortless. Its value comes from helping you become more informed and more deliberate, not from removing uncertainty. Used with that expectation, it can be a practical first step and a useful companion. Used as a substitute for independent judgment or specialized research, it is likely to feel limited.
4.1
590.00 Reviews
Pros
- Simple interface makes investing approachable for beginners.
- Offers fractional investing
- allowing small starting amounts.
- Educational content helps users understand basic investment concepts.
- Automated investing features can support regular contributions.
- Portfolio tracking makes it easy to monitor performance in one place.
Cons
- Investment choices may be more limited than on larger platforms.
- Fees can reduce returns
- especially for smaller portfolios.
- Market investments carry risk and returns are not guaranteed.
- Some advanced trading tools may be unavailable to experienced investors.
- Availability and features may vary depending on the user's country.


